How to Value an Auto Repair Business When Cash Flow Won’t Sit Still
Let’s say RPM is selling an auto repair building. For this example it’s 5,000 square feet. It’s 5,000 sf the day I visit it. It’s 5,000 sf when I evaluate it. It’s 5,000 sf when I market it, when we negotiate it, and when we close it. That makes real estate easy. The fundamental building block of value for real estate is square footage…and it does not change.
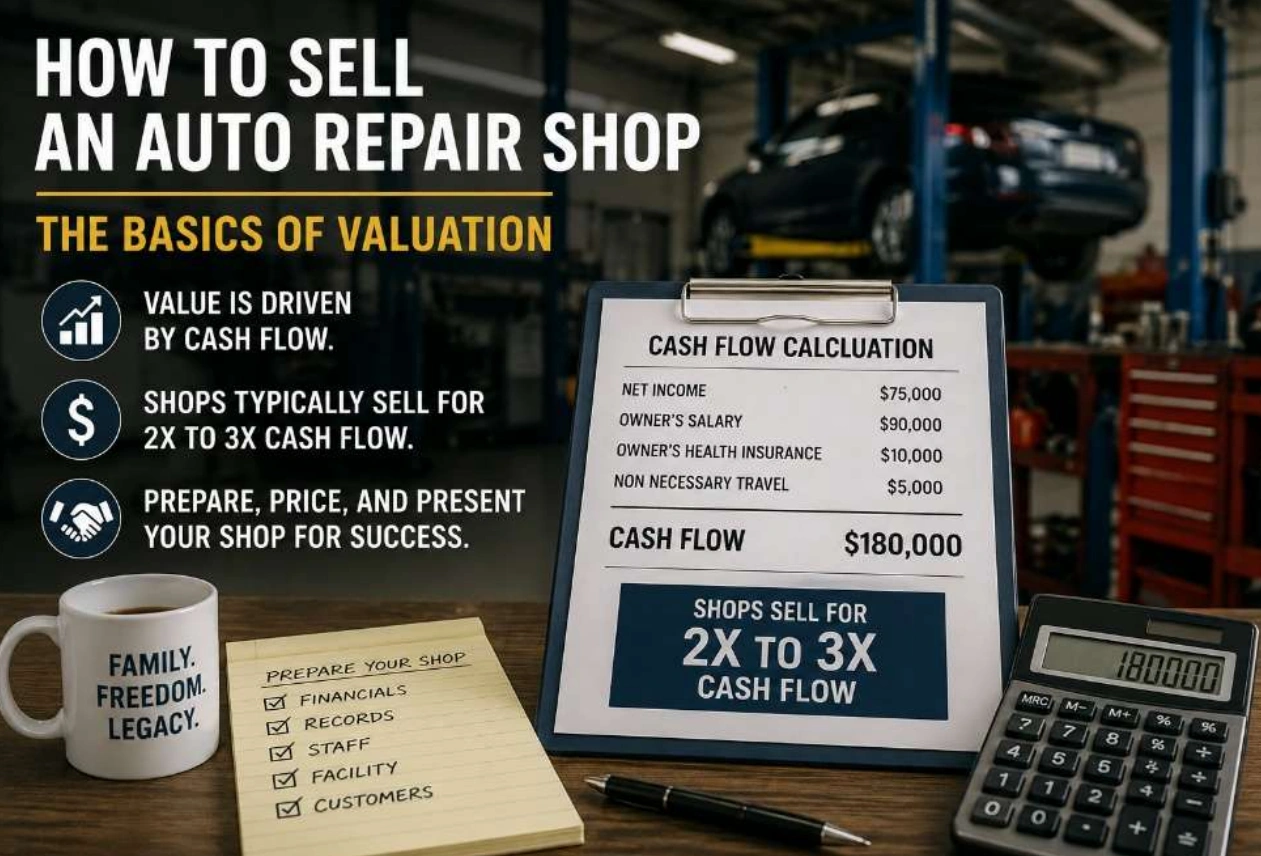
The fundamental building block of value for an auto repair business is cash flow. Sometimes it’s called Seller’s Discretionary Earnings (SDE). Either way…that number does change. It changes from the day I walk in the door to the day we sit down at the closing table. And that’s what makes valuing a shop a moving target.
So how do you hit a moving target? If you’re trying to figure out how to value a mechanic shop when the numbers keep changing…here’s how we handle it.
Start with Last Year
The last fiscal year carries the most weight. Usually that’s the calendar year. Take the cash flow from that year, multiply it by three, and you’ve got a good starting point for an asking price.
Simple enough. But what happens when this year doesn’t look like last year?
What If This Year Is Down?
The first thing a broker should do is ask why. Underline this. Don’t just accept the lower number and don’t ignore it either. Find out what happened.
If it was a fixable problem and it has been fixed…then you can usually still ask 3x on the previous year’s cash flow.
Here’s a good example. A shop has a great service writer who retires. The business goes three months without a service writer, and the owner has to step in and run the counter himself. That’s going to cause a downturn. It just is. The owner can’t be in two places at once.
Now the shop has hired a new service writer, and he’s even better than the old one. If there’s evidence of that…like an increase in the average repair order (RO)…then your problem is mostly solved. The dip had a cause, the cause is gone, and you can show that the business is back on track. That’s a story a buyer will accept. He will accept it because it’s true.
What If Last Year Was the Bad Year?
Here’s a different situation. Let’s say a shop had cash flow of $300k in 2023. It had $300k again in 2024. Then 2025 came in at $250k.
Do we still take the most recent fiscal year? Maybe. But look at what’s at stake:
2023 and 2024 Cash Flow $300k at 3x is a $900k asking price. 2025 Cash Flow $250k at 3x is a $750k asking price.
That’s a $150k difference in asking price. That’s real money to a seller. So before we just take the $250k and move on…where are we at this year, year to date?
If the shop is back at $300k, expressed annually, then use $300k as the cash flow. The down year is bookended by higher cash flow on both sides. In that case we can relax the usual rule of going with the last full fiscal year.
The theme here is: what can we defend? There has to be some plausibility. I can’t just pick the best number I can find and hope nobody notices. A buyer is going to look at it. A lender is going to look at it very closely. But when a down year sits between two stronger periods, and the current numbers back that up…that’s a number I can defend.
How Much YTD Do We Have?
This leads to the next question. How much year-to-date information do we actually have?
One month? That’s no help. Anything can happen in one month.
Three months? Not much help. But here’s the way I approach Q1 results. They may not count for much on their own, but they’re building to a whole. And I’d rather be ahead than behind.
Six months? It’s still not real. But at six months, I usually say it’s starting to become real. Half the year is in the books, and a pattern is starting to take hold.
Crossing September 30
When we cross Q3 at September 30, things change. Now we need to start bracing for what that year will bring.
If you’re reading this in September…this is you. Pay attention.
Let’s say the current year is running ahead of last year, and I’m marketing the deal right now, and it’s still not under LOI. Here’s what I tell the buyer: we are coming in ahead of last year. The YTD numbers are in the act of supplanting the previous year. And by the time we close, the current year will be the new 12-month year anyway.
Think about that. A deal that goes to LOI in October still has to get through due diligence, lender approval, and closing. By the time all that happens, the calendar has turned. The buyer isn’t buying last year’s shop. He’s buying this year’s shop. And if this year’s shop is making more money…that’s the number that matters.
The Bottom Line
Real estate stands still. A business doesn’t. The square footage of the building will be the same at closing as it was on the day I first walked through it. The cash flow will not. The cash flow will change.
So if you’re asking how to value an auto repair business, the answer isn’t just taking one number and multiplying it by three. You gotta look closer. You have to ask why a year was down. You have to look at what came before it and what’s happening now. You have to know how much weight to give the YTD numbers based on how much of the year is behind you. And you have to know when the current year is about to become the year that counts.
All of these are ways to handle a cash flow number that is a moving target. And they all come back to the same question: what can we defend?
Every shop is different, and every year is different too. That’s why at RPM Shop Sales we really try to get to know the shop when we price it out. We only sell auto repair shops, and we know how to tell your shop’s story in a way that buyers and lenders will believe. If you’re thinking about selling, now or in a few years, give us a call.